
Starting your credit journey on the right foot
A good credit history is one of the factors that can improve an individual’s chances of accessing financing, influencing whether a loan is approved, how much can be borrowed, and the terms offered by financial institutions. For young adults with little or no borrowing history, establishing a credit profile early can help pave the way for future borrowing.
A credit score gives lenders an indication of how a person has managed credit and the level of risk associated with lending to them. A weaker credit profile could make it more difficult to qualify for loans or secure favourable borrowing terms. The importance of establishing a credit history is becoming more pronounced as financial institutions increasingly rely on technology to assess borrowers. Senior business development manager at CRIF, Keith Parkes, said the growing use of automated lending systems could eventually see credit reports become the primary basis for lending decisions.
“There’s going to be a time when there is no adjudication, other than the credit report,” Parkes said at a JN Bank Smarter Credit forum.
Parkes explained that financial institutions use information supplied by credit bureaus, alongside their own assessment criteria, in automated systems that analyse applicants’ credit profiles to help determine their eligibility for financing and how much they may borrow. He also pointed to the growing use of artificial intelligence (AI) and data analytics in assessing borrowers at different stages of their financial lives. For individuals with little or no borrowing history, however, establishing a credit profile can be challenging. Acting business relationship and sales manager at JN Bank, Karon Lewis said a few months of loan repayments may not provide enough information for lenders to assess how a borrower would manage a larger loan.
“A couple of months of repaying a loan is not tantamount to sufficient credit history for a bank to go by,” Lewis explained.
Having little or no credit history, however, does not necessarily mean someone has a poor credit record. A credit bureau may return a ‘no hit’ report for someone who has never borrowed. While the report may contain basic identifying and other available information, it does not contain an established borrowing and repayment history for lenders to assess. Lewis advised first-time borrowers to start with a manageable facility and build their credit history gradually.
“If you want to start building credit, I always say to people, start out small,” he said. “No bank wants to be the guinea pig. At some point in time, we don’t have any history to say you’ve had a $2-million loan before. We don’t know how you will accommodate this significant loan,” Lewis added.
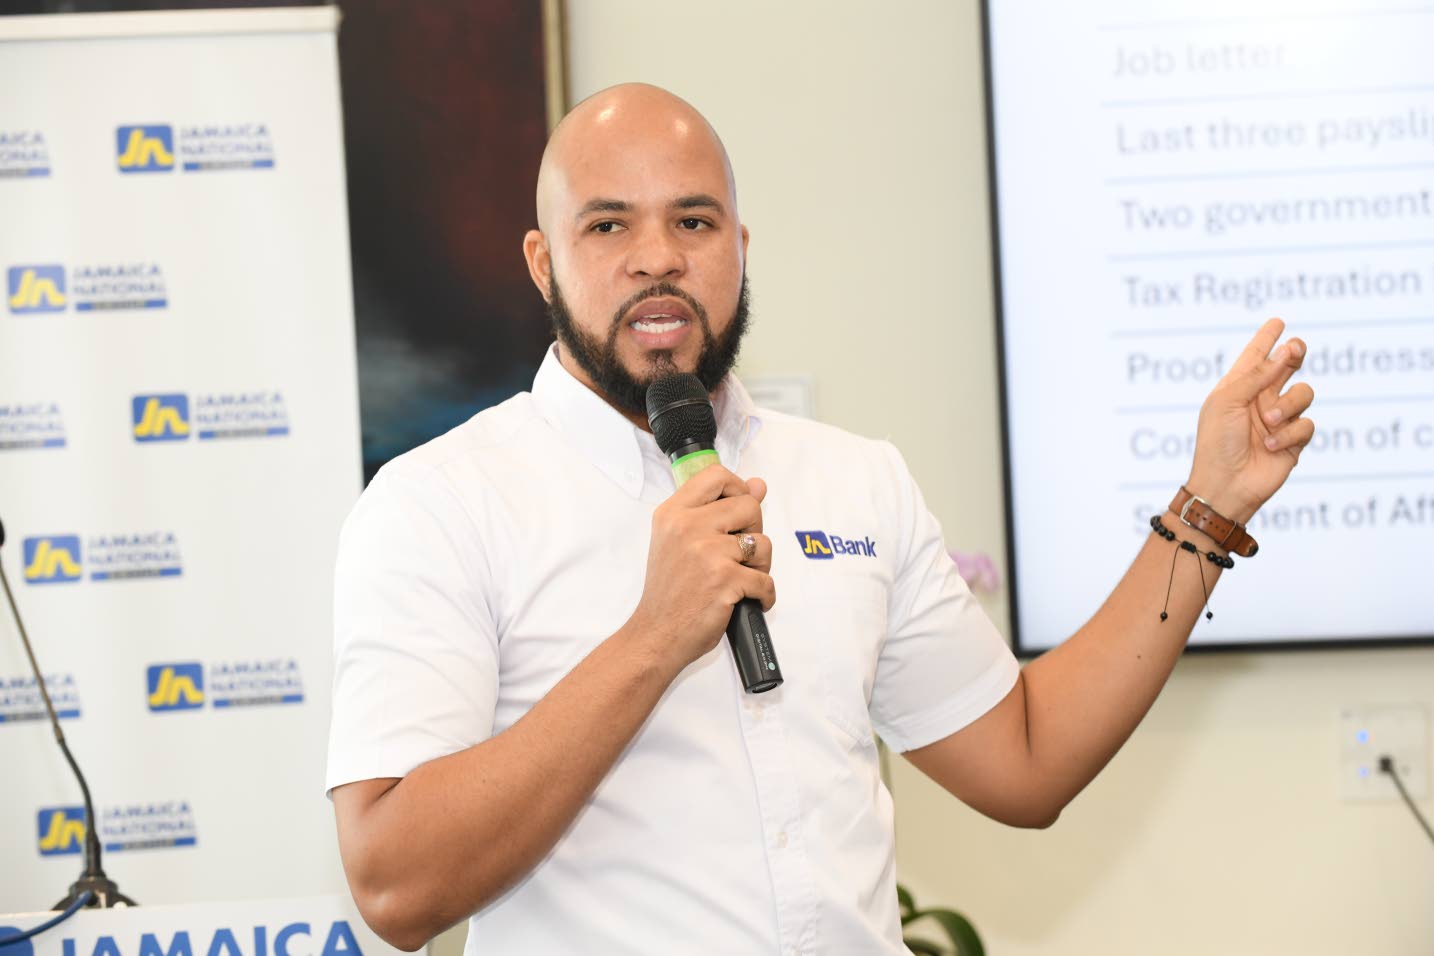
LEWIS… no bank wants to be the guinea pig. At some point in time, we don’t have any history to say you’ve had a $2-million loan before. We don’t know how you will accommodate this significant loan
While payment history is an important factor in determining a borrower’s credit score, not all information appearing on a credit report contributes to the calculation. This includes information on utility and telecommunications accounts, such as arrears and outstanding balances. Hard enquiries made by credit institutions, frequent credit applications within a short period, and high credit card utilisation can also affect a borrower’s score. Utilisation refers to the proportion of available credit being used. Parkes illustrated this using a borrower with a $1 million credit card limit who consistently uses $900,000, or 90 per cent of the available credit.
“That would negatively impact your credit score,” he said.
Parkes also advised credit card users to pay attention to their statement dates, in addition to payment deadlines. Although paying the outstanding balance by the due date helps avoid late payments, the balance recorded when information is reported to the credit bureau can also affect the utilisation reflected in a borrower’s credit profile.
“Once you make that payment on time by the due date and also by the time the statement is run again…between you paying off the outstanding amount in full and the statement running for that period showing that your credit card is fully paid up, then you won’t have a problem,” Parkes explained.
For young adults preparing to access credit for the first time, understanding their credit reports and managing smaller credit facilities responsibly can help establish a borrowing record that lenders can assess when considering future applications.
Consumers are also encouraged to check their credit reports to understand how lenders view their credit history and identify any inaccuracies. Every Jamaican adult is entitled to one free credit report annually, although this does not include a credit score. EveryData Jamaica also provides access to credit reports and scores through its MyEveryData online portal and is currently waiving fees for its paid report options, including those with credit scores, for a limited time.


