
Inflation — the biggest economic risk of the decade
FORMER Chair of the US Federal Reserve, Jerome Powell, famously described inflationary shocks in the immediate post-pandemic period as “transitory” in response to severe supply chain disruptions occ
asioned by COVID-19.
Since then, however, the 2020s have been replete with successive inflationary pressures driven by a series of global disturbances — the COVID-19 pandemic was swiftly followed by Russia’s invasion of Ukraine in 2022, severely affecting agricultural commodity prices. While there was a relative lull in adverse global activity for the next two years as post-pandemic demand was gradually released and inflation decelerated, shifts in US trade and tariff policies in 2025 and renewed geopolitical tensions in the Middle East in 2026 have threatened to drag the world into a period of stagflation, with heightened volatility in international energy prices triggering a downward revision in growth forecasts for the globe’s largest economies.
Meanwhile, the world seems set to resume a cycle of monetary tightening for the foreseeable future after a truncated period of financial easing with some of the world’s largest Central Banks — including the US Fed, the European Central Bank and the Bank of Japan — aggressively moving to get ahead of the latest round of global inflation and signaling further increases on the horizon. Inflationary shocks over the last half-decade have been anything but transitory and have become so structurally embedded in the global economy that they could be described as a “new norm.”
Jamaica’s historical experience with inflation
These inflationary events have kept the Bank of Jamaica (BOJ) busy over the last few years as it aims to achieve its mandate of ensuring price stability by keeping price increases low and predictable. However, external upheavals, over which the Central Bank has no control, have made meeting the inflation target of 4 to 6 per cent much harder. As measured monthly since March 2020, 12-month point-to-point inflation has exceeded the upper band of 6 per cent on 33 occasions, or 42 per cent of the time.
Meanwhile, it has dipped below 4 per cent nine times, giving the Bank a success rate of 46 per cent in meeting its target, or in 36 of the previous 78 months up to August 2026. The highest rate of inflation in this sequence occurred in April 2022, when it hit 11.8 per cent- in the middle of a 20-consecutive month period during which inflation surpassed 6 per cent, ending in March 2023. This was later followed more recently, however, by a 21-month period during which inflation fell below the upper band of 6 per cent. This trend was interrupted in June 2026 as the effects of the outbreak of the US-Israel-Iran war in February started to filter through to domestic prices.
The Bank’s efforts to keep prices within target have unequivocally been affected by supply-side issues. In the three years between the start of the BOJ’s inflation targeting regime in April 2017 and the onset of COVID-19 in March 2020, the inflation target was breached only once — in December 2019 — when the inflation outturn was 6.2 per cent. As a result, this 97 per cent success rate prior to the pandemic has been pulled down to 50 per cent when the full period from April 2017 to August 2026 is assessed. This highlights the primarily exogenous supply-driven, rather than demand-induced, nature of inflation experienced in Jamaica. This is made more evident by our unusual combination of single-digit inflation and unemployment for the last few years, which seems to defy the conventional laws of economics as they traditionally share an inverse relationship.
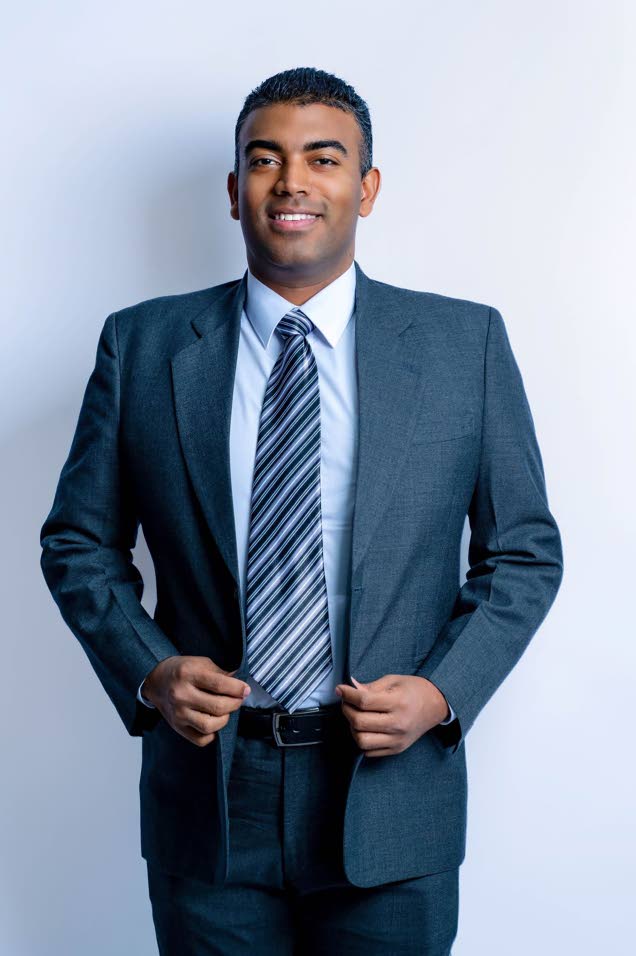
Falconer
The consistent attainment of full employment should result in the overheating of the economy because of increased earning power and spending capacity, fueling demand-driven inflation. The implication of simultaneously low unemployment and inflation, however, is that the reduction in unemployment is insufficient to drive any appreciable inflation through increased domestic demand. This could be because most of the increase in the employed labour force is in jobs which are remunerated below the median wage. Nevertheless, these low figures are significant departures from Jamaica’s historical experience with both unemployment and inflation. Jamaica only achieved single-digit unemployment in 2007 — 45 years after Independence. Meanwhile, if a 6 per cent upper inflation target existed prior to April 2017, Jamaica would have eclipsed it 77 per cent of the time, as measured monthly since Independence.
Why inflation feels different for everyone
Therefore, relative to the first 55 years of Independence, price stability has taken a much different trajectory over the last decade. However, cost-of-living pressures persist. The Consumer Price Index (CPI), and therefore the general price level of goods and services, has increased by 67 per cent since inflation-targeting began in April 2017, and by 48 per cent since COVID-19 in March 2020. Headline inflation, however, only tells part of the story. As an average of the price increases for nearly all goods and services in the economy across all transactions involving those price increases for the entire island, it conceals variations across specific purchasing locations, household composition and the quantities of items consumed. Consequently, the price increases experienced by individuals may be significantly more (or in some instances less) than the targeted headline inflation rate of 4 to 6 per cent when met.
The CPI is calculated from Statin’s Household Expenditure Survey (HES), which is revised periodically to reflect changes in consumer items and their consumption patterns. The latest edition in 2017 (which will soon be updated) includes additional items that were not captured in the previous edition in 2005 as expenditure trends evolved over the interval. Categories are also weighted differently. The most heavily weighted category is Food, followed by the category covering Housing, Water and Electricity; then Transport. In total these three areas account for 55 per cent of the total inflation basket and most Jamaicans will likely have the largest portion of their overall consumption in these areas. However, if someone buys fewer amounts of the most heavily weighted categories and more of those that are weighted less, then the level of inflation they experience may be less. And vice versa.
Personal preferences, tastes, lifestyle and mobility also influence the personal inflation experience. The CPI may not necessarily reflect price changes that affect a particular individual or groups of people at a particular time. The demand elasticity of purchases also matters — consumers tend to place more emphasis on the price changes of goods that they buy more frequently than those they may purchase only occasionally.
However, regardless of individuals’ inflation experience and their respective buffers to withstand them, Jamaica will need to collectively prepare to navigate an elevated inflationary environment for the rest of the decade.
Keenan Falconer is an economist with experience in the Jamaican private and public sectors and the multilateral financing space.


